
DCF valuation estimates what a business or share is actually worth by discounting every dollar of expected future cash flow back to today's terms, using the formula V₀ = Σ FCFt/(1+r)^t. Run correctly, the output is enterprise value, the value of the whole operating business before debt; subtract net debt and other claims and divide by shares outstanding to reach a per-share figure. The sections below walk through building that model step by step, choosing the right discount rate, and stress-testing the result so a single number never masquerades as certainty.
TL;DR:
- Most DCF valuations depend heavily on conservative assumptions for long-term growth and discount rates, with small changes potentially causing large valuation swings.
- Using free cash flow to the firm (FCFF) with WACC is the standard approach for most professional analysts, while FCFE suits companies with stable leverage and dividend policies.
- Building a transparent model with separate inputs, forecasts, discounting, and terminal value sections ensures accuracy and ease of updates.
- Conducting sensitivity analyses on terminal growth and discount rates helps prevent overconfidence in a single point estimate and better reflects valuation uncertainty.
- Comparing DCF results with real-time market data and alternative valuation methods helps verify assumptions and avoid common modeling errors.
What Does DCF Valuation Actually Measure?
DCF valuation measures intrinsic value: what a company is worth based on the cash it can generate, independent of what the market happens to be paying for it today. That distinction separates DCF from comparable-company multiples, which price a stock relative to peers rather than its own cash-generating ability. Aswath Damodaran frames this as valuing a business on its fundamentals rather than sentiment, which is exactly why the method holds up even when markets are volatile or mispricing an entire sector.
That intrinsic-value focus makes DCF useful in a handful of recurring situations:
- Long-term equity research, where you want a price target independent of current market mood
- M&A and private transactions, where there is no public multiple to lean on
- Capital budgeting, evaluating whether a project or acquisition clears its cost of capital
The tradeoff is sensitivity. Small changes to growth or the discount rate can swing the output by a wide margin, a limitation covered in depth later in this guide. For now, treat DCF as a rigorous starting estimate, not a precise price.
FCFF or FCFE: Which Cash Flow Should You Forecast?
Free cash flow to the firm (FCFF) is cash available to all capital providers, debt and equity alike, and it typically starts from EBIT(1 − tax rate) plus depreciation, minus capital expenditures and working capital investment. Free cash flow to equity (FCFE) strips out obligations to debt holders first, leaving what is available to shareholders alone.
CFA Institute research on analyst practice shows why FCFF dominates in professional use:
- 78.8% of analysts use a DCF approach for equities, and 86.9% of those rely on a discounted free cash flow model
- FCFF is used roughly twice as often as FCFE among that group
- FCFF handles changing leverage cleanly, since capital structure shifts don't distort the operating cash flow itself
- FCFE fits better when a company has a stable, predictable capital structure and dividend policy
The choice dictates your discount rate: FCFF gets discounted at the weighted average cost of capital (WACC), while FCFE gets discounted at the cost of equity alone. Mixing the two, discounting FCFF at cost of equity or vice versa, is one of the most common errors in student and analyst models, as Damodaran's valuation text points out directly.
How Do You Build a DCF Model Step by Step?
Building a DCF model follows a consistent sequence, whether you're valuing a mature industrial company or a fast-growing software business. Wall Street Prep's six-step framework is the industry-standard structure, and it maps cleanly onto a spreadsheet:
- Pick a forecast horizon. Most practitioners use five to ten years of explicit forecasts, long enough for the business to reach a steady state but short enough that your assumptions stay grounded.
- Build revenue drivers. Use a top-down approach (market size times share) for early-stage or cyclical companies, or bottom-up (unit volume times price) when you have granular operating data.
- Forecast margins, capex, and working capital. These three levers, combined with tax rate, convert revenue into unlevered free cash flow.
- Compute FCF for each forecast year, then lay out a discounting schedule that applies your chosen rate period by period.
- Calculate terminal value for everything beyond the explicit forecast, and discount it back to today alongside the interim cash flows.
- Add non-operating assets and adjust for debt to move from enterprise value toward a defensible per-share number.
Structure your spreadsheet with a dedicated inputs tab, a clean forecast table, a separate discounting schedule, and a clearly labeled terminal value block. Keeping these separate, rather than burying formulas inside one another, is what makes a model auditable months later.
Pro Tip: Color-code every hardcoded input in blue and every formula-derived cell in black. It takes thirty seconds and saves hours when you or a colleague revisit the model to update assumptions.
How Do You Choose a Discount Rate for a DCF?
The discount rate has to match your cash flow definition: WACC for FCFF, cost of equity for FCFE. WACC blends the cost of debt and the cost of equity, weighted by their market values, not their book values, since book weights can badly misstate a company's actual capital structure.
Cost of equity typically comes from the Capital Asset Pricing Model (CAPM): the risk-free rate plus beta times the equity risk premium, with adjustments layered in for country risk or small-company size premiums where relevant. A few points trip up even experienced modelers:
- Using a raw, unadjusted beta pulled from a data provider without checking whether it reflects the company's current leverage
- Applying book-value debt-to-equity weights instead of market-value weights, which understates or overstates leverage
- Forgetting that private companies need adjustments most public-company betas don't require
Wall Street Prep's guidance on deriving market-value weights is worth following closely here: a WACC built on stale book weights can shift a valuation by several percentage points, which cascades through every discounted cash flow in the model.
Perpetuity Growth or Exit Multiple: Which Terminal Value Method Wins?
Terminal value often accounts for the majority of a DCF's total value, according to CFI's modeling guide, which is exactly why it deserves as much scrutiny as your explicit forecast years.
The perpetuity growth method assumes cash flow grows at a constant rate forever, using TV = FCFn × (1+g) / (r − g). Keep g conservative, generally at or below long-run GDP growth or inflation, since assuming a company outgrows the entire economy indefinitely is not a defensible long-term claim.
The exit multiple method instead applies a valuation multiple (EV/EBITDA, for example) to a projected final-year metric, based on how comparable companies trade today. It's often easier to defend to a skeptical audience because it's anchored to observable market pricing.
- Perpetuity growth works best for stable, mature businesses with predictable long-run margins
- Exit multiples work well when good comparables exist and you want to cross-check against current market pricing
- Always run both methods side by side; a wide gap between them is an early warning that one set of assumptions is off
Because terminal value carries this much weight, sensitivity testing it isn't optional. That's covered in detail further down.
How Do You Convert Enterprise Value Into a Per-Share Price?
Enterprise value tells you what the operating business is worth, but shareholders need a per-share number, and getting there requires several deliberate adjustments.
- Add non-operating assets: excess cash, investments, or non-core real estate not captured in your cash flow forecast
- Subtract net debt, along with preferred stock, pension shortfalls, and other financial claims senior to common equity
- Adjust for minority interests, since consolidated financials often include cash flow attributable to stakes you don't own
- Account for dilution from options and convertible instruments, which can meaningfully inflate the effective share count
- Divide the resulting equity value by diluted shares outstanding, using a share count as close to the valuation date as possible
A free enterprise value calculator can help confirm these adjustments land correctly, and comparing enterprise value to market capitalization directly is a useful gut check before you finalize a per-share estimate.
How Should You Stress-Test a DCF Valuation?
A single DCF output is a guess dressed up as a number. The fix is presenting a range, built from structured sensitivity and scenario work, rather than one point estimate.
A two-way sensitivity table, WACC across the top and terminal growth rate down the side, is the fastest way to see how much your valuation actually moves. A typical layout looks like this:
| Terminal Growth | — | — | — |
|---|---|---|---|
| — | Highest value | Mid value | Lower value |
| — | Higher value | Base case | Lower value |
| — | Highest value | Mid value | Lowest value |
Beyond that grid, build out base, bull, and bear scenarios that flex revenue growth, margin trajectory, and capex intensity together, then visualize the spread with a football-field chart or a tornado diagram ranking which input moves the valuation most. Damodaran's own commentary treats this kind of scenario work as essential precisely because valuation accuracy depends so heavily on input quality.
Pro Tip: Use the sensitivity range, not the base case, to set your margin of safety. A stock only clears your bar when it looks attractive even under your bear-case assumptions.
What Are the Most Common DCF Mistakes to Watch For?
Most flawed DCFs fail for the same handful of reasons, and none of them require a modeling error to appear:
- Garbage-in, garbage-out: an unrealistic revenue growth assumption or margin trajectory quietly wrecks every downstream number
- Overweighting terminal value without questioning whether the growth rate or exit multiple is actually defensible
- Mismatching discount rate and cash flow type, discounting FCFF at cost of equity or FCFE at WACC
- Treating a single-point output as precise rather than presenting a range
Cross-checking a DCF against market multiples catches most of these before they become a bad investment decision. It's why CFA Institute research finds 92.8% of analysts pair DCF with multiples rather than relying on discounted cash flow alone. Document every assumption in your inputs tab so anyone reviewing the model, including future you, can see exactly what drove the number.
What Should Your DCF Excel Model Actually Include?
A reproducible DCF model needs a specific set of exposed cells, not buried formulas scattered across a dozen tabs. Building it once with the right structure means every future update, whether it's new quarterly results or a revised growth thesis, takes minutes instead of hours.
- Inputs tab: revenue growth rate by year, gross and operating margin assumptions, capex as a percent of revenue, working capital change, tax rate, WACC components, and terminal growth or exit multiple
- Forecast tab: revenue build, EBIT, taxes, depreciation, capex, and working capital feeding into unlevered free cash flow line by line
- Discounting schedule: mid-year or year-end discounting convention applied consistently, since mixing conventions mid-model understates or overstates present value
- Terminal value block: both perpetuity growth and exit multiple calculated side by side for comparison
- Bridge to equity value: net debt, non-operating assets, minority interest, and diluted share count clearly laid out
| Checklist item | Why it matters |
|---|---|
| All hardcoded inputs isolated on one tab | Prevents assumptions from hiding inside formulas |
| Mid-year discounting convention applied consistently | Avoids understating present value of near-term cash flows |
| Terminal value shown via both methods | Flags when one assumption is out of line with the other |
| Version and date stamped on the file | Lets you track how the valuation shifted as actuals came in |
| Peer or second-pass review before acting on the output | Catches formula errors a single builder tends to miss |
Once actual quarterly results come in, refresh the model rather than starting over. Recalibrating with real numbers, updated margins, actual capex, revised growth, keeps a DCF from drifting into fantasy the way static models often do six months after they're built. A valuation checklist mapped to calculators can help keep the update process consistent every time.
How Tickerplace Tools Map to Each DCF Step
Building a full DCF by hand is valuable for learning, but checking your work against a live data feed catches errors a static spreadsheet won't. Tickerplace's intrinsic value calculator gives a fast cross-check against your own discounted cash flow output, while the enterprise value calculator helps confirm your net debt and non-operating asset adjustments are landing correctly. With daily updated coverage across US and ASX-listed companies, these tools reduce the manual data-pulling errors that quietly distort otherwise sound models, particularly around share counts and current net debt figures.
Why Most DCF Guides Get the Emphasis Wrong
Most DCF tutorials spend 80% of their word count on the discounting mechanics and almost nothing on where the real damage happens: unrealistic terminal growth assumptions and a discount rate that doesn't match the cash flow definition. The math of discounting a cash flow is trivial. Getting the inputs right, and being honest about how little confidence you should have in a single-point output, is the actual skill.
The conventional advice to "run a DCF and get your target price" undersells how much a small change in terminal growth can swing that price. A model showing one number to the cent is usually less trustworthy than one that openly presents a range across three or four scenarios. If you take one thing from this guide, prioritize sensitivity testing over precision in your base case. A DCF is a framework for disciplined thinking about a business's cash generation, not a crystal ball, and treating it that way from the start avoids the overconfidence that sinks most first-time models. Pairing the canonical CFA and Damodaran approach with a quick tool-based cross-check is a sound habit, not a shortcut.
— Tickerplace
Check Your DCF Output Against Live Market Data
Building a DCF by hand teaches you the mechanics, but confirming your output against real-time data is what turns a classroom exercise into an investment decision you can act on. A platform can provide a daily updated intrinsic value estimate, calculated using DCF alongside P/E and P/S models, for thousands of US and ASX-listed companies, without subscription fees institutional platforms charge for similar data.
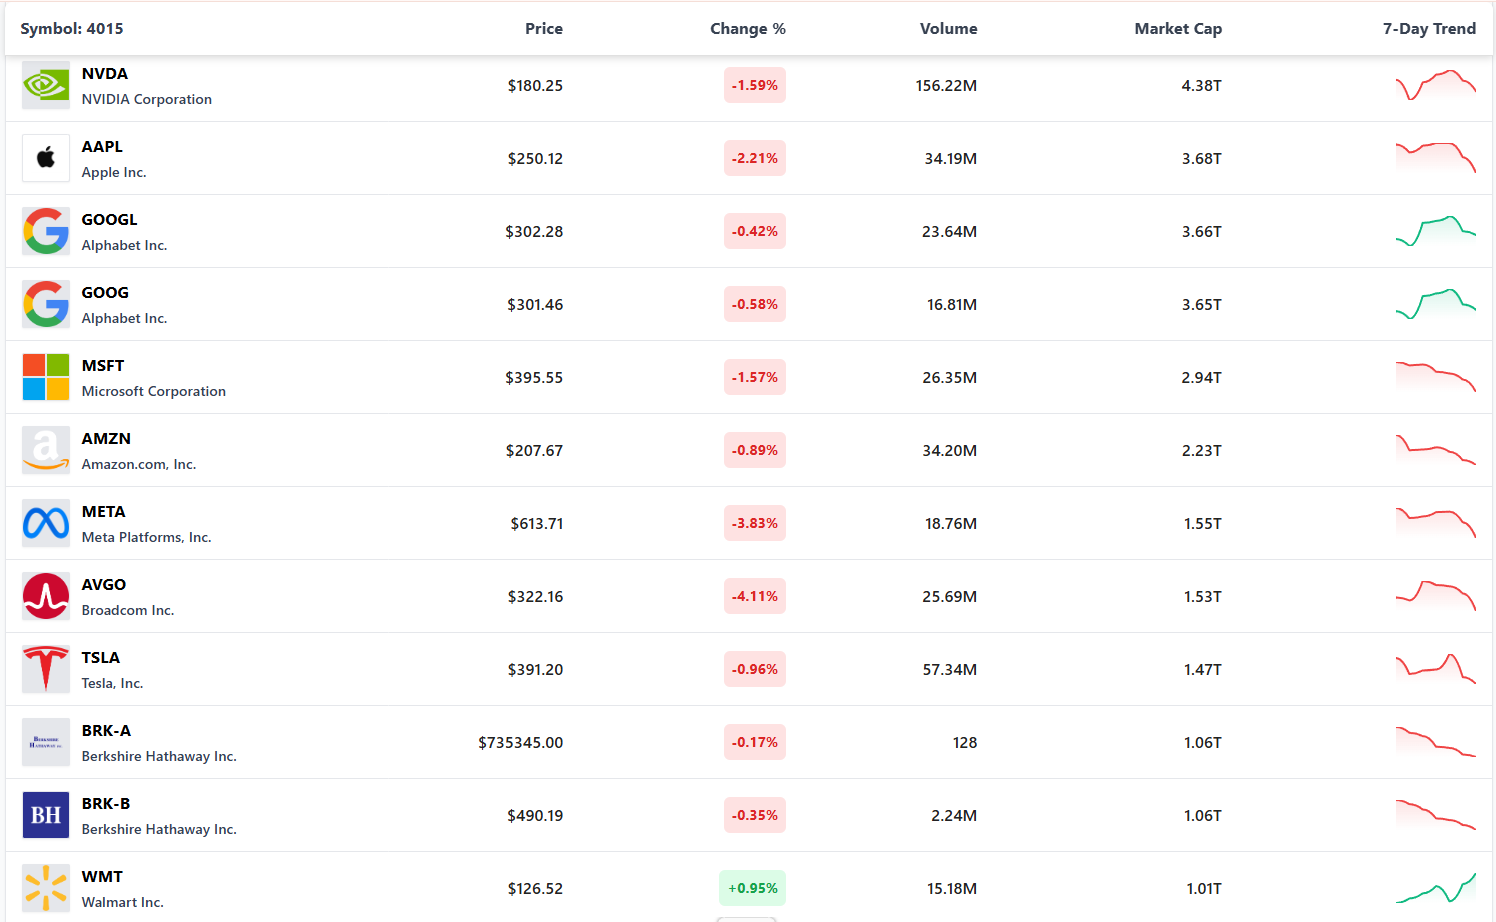
If you've just built your own model, run it against the intrinsic value calculator to see where your assumptions diverge from the market-implied consensus. Prefer a faster gut check before you build anything? The stock valuation checker tells you in seconds whether a stock is trading above or below its estimated fair value. Either way, start by pulling up the ticker you're analyzing and comparing your number to ours.
Sources
- Free Cash Flow Valuation | CFA Institute
- DCF Model Training | Wall Street Prep
- Aswath Damodaran — valuation commentary (ch.2)
FAQ
What is the DCF method of valuation?
DCF valuation estimates a company's intrinsic value by forecasting its future free cash flows and discounting them to present value using the formula V₀ = Σ FCFt/(1+r)^t, where r is the appropriate discount rate for the cash flow type chosen.
Are DCF and NPV the same thing?
Not quite. DCF is the discounting process itself, while NPV equals the present value of those discounted cash flows minus the initial investment or purchase price, a distinction that matters when evaluating a specific project versus valuing an entire company.
How do you do a DCF step by step?
Forecast unlevered free cash flow for five to ten years, calculate a terminal value using perpetuity growth or an exit multiple, discount everything back at WACC or cost of equity depending on your cash flow type, then add non-operating assets and subtract net debt to reach equity value per share.
How accurate is a DCF valuation?
A DCF is only as accurate as its inputs, and small shifts in growth or discount rate assumptions can swing the output substantially, which is why practitioners present a sensitivity range rather than a single number and cross-check the result against market multiples before relying on it.