
Cash flow statement analysis examines the operating, investing, and financing sections of a company's cash flow statement to determine whether it actually generates the cash it needs to run and grow. The single most useful check for any business owner, analyst, or investor is whether operating cash flow consistently exceeds current liabilities and capital spending, since operations, not financing or asset sales, is the only sustainable source of liquidity.
TL;DR:
- Consistently positive operating cash flow exceeding current liabilities and capital spending indicates sustainable liquidity, especially when it rises with revenue over multiple years.
- Watch for operating cash flow lagging net income, rising receivables or inventories, and reliance on debt or equity issuance to cover shortfalls, signaling potential financial stress.
- Free cash flow generated after capital expenditures provides a clearer view of actual cash available for debt repayment or dividends, particularly when investments are growth-driven rather than maintenance.
- Analyzing key ratios like operating cash flow ratio, free cash flow, and cash flow margin over several periods reduces the impact of one-off or timing distortions in single reports.
- Using tools that compare multi-year financial statements and calculate discounted cash flow assumptions accelerates valuation and improves decision accuracy.
What Are the Three Sections of a Cash Flow Statement?
Every cash flow statement breaks activity into three buckets, and knowing what belongs in each one is the foundation of cash flow analysis: operating, investing, and financing. Operating cash flow captures cash generated from core business activity: cash collected from customers, cash paid to suppliers and employees, and interest or tax payments. Investing cash flow reflects capital allocation decisions such as purchases of equipment, acquisitions, or proceeds from selling a division. Financing cash flow shows how the company funds itself: new debt issuance, share buybacks, dividend payments, and loan repayments.
Companies present operating cash flow using one of two methods. The direct method lists actual cash receipts and payments, while the indirect method, the format most public companies use, starts with net income and adjusts for non-cash charges like depreciation and changes in working capital. Both arrive at the same net operating cash flow figure, but the indirect method requires you to trace the adjustments to understand what is actually driving the number.
A few presentation quirks deserve a second look before you trust the headline figures:
- One-off asset sales can inflate investing cash flow in a single quarter and disappear the next, so check whether a "positive" investing section reflects normal capex or a one-time divestiture.
- Reclassifications between operating and investing activities occasionally shift year-over-year comparisons; read the notes when a line item moves categories.
- Non-cash charges, including stock-based compensation add-backs, can make operating cash flow look stronger than the underlying cash economics suggest.
Reading the footnotes is not optional here. Companies frequently disclose the details behind working capital swings, asset impairments, and financing arrangements in notes rather than on the face of the statement itself.
Why Does Profit Not Guarantee Positive Cash Flow?
Profit is an accounting construct built on accrual rules; cash flow is what actually moved in and out of the bank account. A company can report solid net income while burning cash if receivables are piling up, inventory is growing faster than sales, or depreciation is masking the real cost of maintaining aging equipment. That gap between reported profit and operating cash generation is often the first place trouble shows up, and reconciling the two is a standard diagnostic for assessing earnings quality.
Multi-period patterns tell you more than any single year. A business with operating cash flow rising alongside revenue, modest and predictable capital expenditures, and financing activity limited to routine debt service is generally healthy. Watch for the opposite pattern: a company that repeatedly plugs cash shortfalls with new borrowing or fresh equity issuance while operating cash flow stagnates or declines. Asset sales that consistently outpace new investment can also mask a business that is quietly shrinking rather than growing.
Here is a compact checklist of red flags worth chasing down in the filings or on an earnings call:
- Operating cash flow that lags net income for two or more consecutive periods.
- Receivables or inventory growing meaningfully faster than revenue.
- Rising reliance on financing activities to cover operating or investing needs.
- Capital expenditures that fall sharply, which can flatter free cash flow while starving future growth.
- Frequent "non-recurring" adjustments that recur every year.
Pro Tip: When operating cash flow and net income diverge for more than one reporting period, pull up the working capital line items first. Ballooning receivables or slow-moving inventory are usually the quickest explanation, and they show up well before a company admits to a liquidity problem.
Which Cash Flow Ratios Matter Most?
Five calculations do most of the work in quantifying cash-flow health, and each one answers a slightly different question.
- Operating cash flow ratio equals operating cash flow divided by current liabilities. A company with operating cash flow slightly less than current liabilities has an operating cash flow ratio under 1.0, meaning operations alone don't quite cover near-term obligations. A ratio consistently under 1.0 is often the earliest signal of a liquidity problem for small and mid-sized businesses.
- Free cash flow (FCF) equals operating cash flow minus capital expenditures. If a firm generates $2 million in operating cash flow and spends $600,000 on capex, FCF is $1.4 million, the cash actually available to pay down debt, buy back shares, or fund dividends.
- Cash flow margin equals operating cash flow divided by revenue. A company with $10 million in revenue and $1.5 million in operating cash flow has a 15% margin, letting you compare cash efficiency across companies of different sizes.
- Cash conversion cycle measures how many days it takes to convert inventory investment back into cash, calculated as days inventory outstanding plus days sales outstanding minus days payable outstanding. A cycle of 45 days means cash is tied up in the business for roughly six and a half weeks before it comes back in.
- Cash flow coverage ratio equals operating cash flow divided by total debt, showing how many years of current cash generation it would take to retire all outstanding debt.
Single-year figures are noisy. A one-time contract payment, a large tax refund, or a timing shift in supplier payments can distort any of these ratios for a single quarter, so normalize by looking at a three to five-year average where possible, an approach valuation practitioners consistently recommend.
Negative free cash flow is not automatically a warning sign. A company investing heavily in growth capacity, new stores, a distribution center, expanded production lines can post negative FCF for several years and still be building real value, provided the operating cash flow trend underneath is improving. The distinction that matters is whether the capital spending is discretionary growth investment or a defensive scramble to replace failing equipment.
How Do You Analyze a Cash Flow Statement Step by Step?
A disciplined workflow turns cash flow statement analysis from guesswork into a repeatable process you can run in under an hour.
- Gather at least three periods of statements. Pull the cash flow statement, balance sheet, and income statement for three or more comparable periods, and reconcile the ending cash balance on the cash flow statement to the cash line on the balance sheet.
- Review each section separately. Read operating, investing, and financing activities in isolation before drawing conclusions, since each answers a different question about the business.
- Compare periods and compute ratios. Calculate the operating cash flow ratio, free cash flow, cash flow margin, and cash conversion cycle for each period side by side.
- Form hypotheses about anomalies. If receivables jumped or capital expenditures spiked, write down the likely explanation before checking the notes.
- Prioritize next actions. Decide whether the finding warrants tightening collections, renegotiating supplier terms, reviewing loan covenants, or simply monitoring next quarter.
This mirrors the approach outlined in practical small-business cash flow guides, which recommend the same extract, review, compare, calculate, and flag sequence for identifying liquidity issues quickly.
Before closing the analysis, run through this short list:
- Does operating cash flow reconcile cleanly with net income, and if not, why?
- Are capital expenditures growth-driven or maintenance-driven?
- Is financing activity funding expansion or covering a shortfall?
- Do the notes disclose any one-time items skewing a section?
- How do the ratios compare to the same period last year, not just the prior quarter?
Company financial pages that lay out several years of statements side by side, like Tickerplace's financials pages, make step one and step three considerably faster than rebuilding the statements from scratch in a spreadsheet.
What Is the Difference Between FCFF and FCFE?
FCFF, unlevered free cash flow available to all capital providers, and FCFE, levered free cash flow available specifically to equity holders, answer different valuation questions and require different discount rates. FCFF excludes financing impacts entirely, so it reflects pure operating performance regardless of how the company is capitalized. FCFE, by contrast, is sensitive to net borrowing since it adds back new debt issued and subtracts debt repaid.
The formulas, in simplified form:
- FCFF = Net income + non-cash charges + interest expense × (1 − tax rate) − capital expenditures − change in working capital.
- FCFE = Net income + non-cash charges − capital expenditures − change in working capital + net borrowing.
Discount rate selection follows directly from which measure you use. FCFF is discounted at the weighted average cost of capital (WACC) to arrive at enterprise value, since it represents cash available to both debt and equity holders. FCFE is discounted at the cost of equity alone to arrive directly at equity value. Mixing these up, discounting FCFE at WACC, for instance, produces a systematically wrong valuation.
Forecasting either measure for a discounted cash flow model requires more than one year of projections. Analysts typically build a five to ten year explicit forecast, apply a terminal value using a perpetuity growth rate or exit multiple, and then stress-test the result with sensitivity analysis across different growth and discount rate assumptions. A single year's free cash flow carries too much noise to anchor a valuation on its own.
Negative FCFE is not necessarily disqualifying. A company that just issued a large debt tranche to fund an acquisition might show negative FCFE for one period purely because of the financing mechanics, not because the underlying business is deteriorating. In cases like this, analysts often normalize the cash flow by adjusting for the one-time financing event, or lean more heavily on FCFF, which sidesteps the distortion. Tools that compute free cash flow and feed it directly into a discounted cash flow calculator save considerable time compared to rebuilding these projections by hand every time you evaluate a new company.
How Tickerplace Fits Into Cash-Flow-Driven Research
Every step described above, pulling multi-period statements, computing ratios, and running FCFF or FCFE into a discounted cash flow model, can be done manually, but it's slow, and small errors compound quickly across a five-year forecast. Tickerplace's company financial pages lay out operating, investing, and financing activity across multiple periods in one place, which removes most of the manual reconciliation work in step one of the workflow above. The intrinsic value calculator and enterprise value calculator let you plug in FCFF or FCFE assumptions and see the valuation output immediately, rather than rebuilding a discounted cash flow model from a blank spreadsheet.
A tool speeds the mechanical part of the job. It does not replace the judgment call of spotting a one-off asset sale buried in investing activities or a reclassification hiding in the footnotes. Pair the ratio checks and red-flag review covered above with model-based valuation, and use a watchlist to track how fair value estimates shift as new statements come in each quarter.
— Tickerplace
Put These Cash-Flow Checks to Work on Real Stocks
Some platforms offer institutional-grade valuation tools, including DCF, P/E, and P/S models, to individual investors without the subscription costs typically reserved for professional research desks. Once you've worked through a company's cash flow statement using the ratios and red flags covered above, the natural next step is turning that analysis into a valuation.
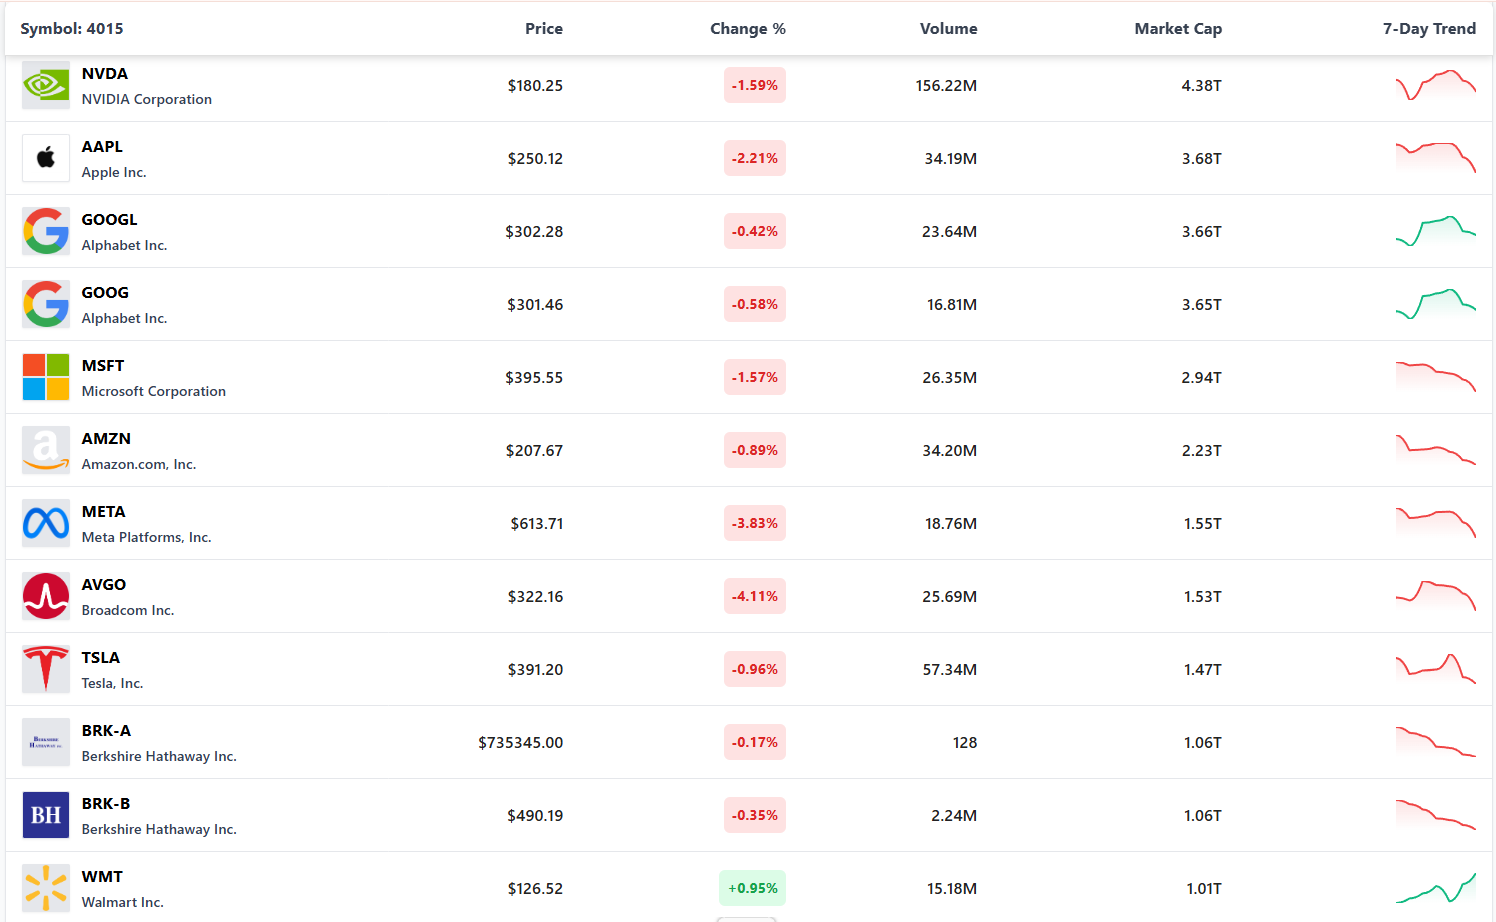
Start by pulling up a company's financial statements to check operating cash flow trends across periods, then run your FCFF or FCFE assumptions through the stock valuation calculator to see whether the stock is trading above or below its estimated intrinsic value. From there, add the ticker to your valuation watchlist so you can track how fair value shifts as new quarterly cash flow data arrives. The core valuation tools are available on the Free Plan at no cost, and Premium, priced at $120 per year, unlocks deeper historical financials and full DCF breakdowns for investors who want to go further.
Sources
For deeper study: Investopedia on cash flow basics, CFA Institute on free cash flow valuation, Corporate Finance Institute on FCFF vs FCFE, and Damodaran's notes on valuation-grade cash flow forecasting. The working capital and financing blog also covers cash conversion mechanics in more depth for business owners.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
How do you analyze a cash flow statement?
Pull at least three periods of statements, review operating, investing, and financing activity separately, compute ratios like the operating cash flow ratio and free cash flow, then flag anomalies for follow-up in the notes or with management.
How do you interpret a cash flow statement?
Positive and growing operating cash flow signals a healthy core business; a pattern of financing activities covering operating shortfalls, or asset sales masking weak operations, signals rising risk.
What are the 5 financial statement analysis techniques?
Common techniques include horizontal analysis (period-over-period comparison), vertical analysis (common-size statements), ratio analysis, trend analysis across multiple years, and cash flow analysis focused specifically on liquidity and cash generation.
How do I know if my cash flow statement is correct?
Reconcile the ending cash balance on the statement to the cash line on the balance sheet, and confirm that net income plus non-cash adjustments and working capital changes ties out to the reported operating cash flow figure.
What does Tickerplace cost to use for cash flow analysis?
Tickerplace's Free Plan has no published price and covers core valuation tools, while Premium costs $120 per year and unlocks full historical financials and deeper DCF breakdowns, as listed on the pricing page.